

MyChoice Benefits
4.7

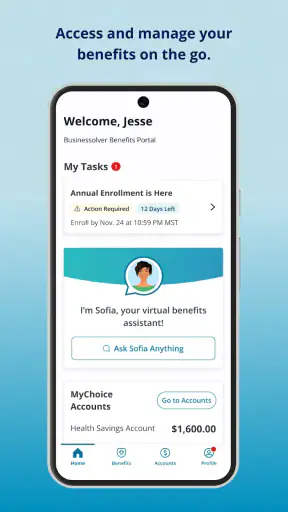
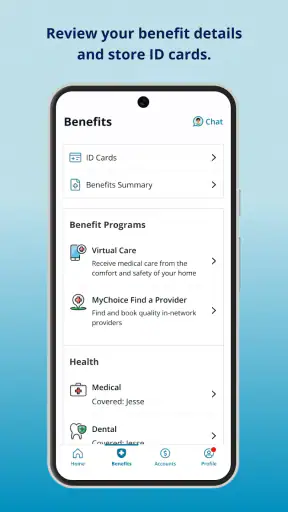
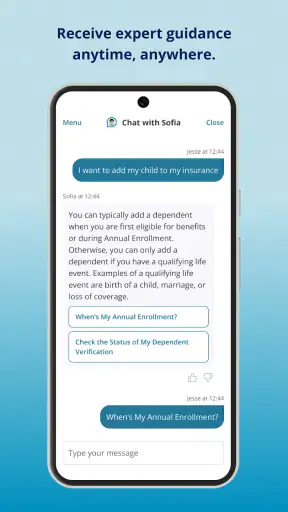
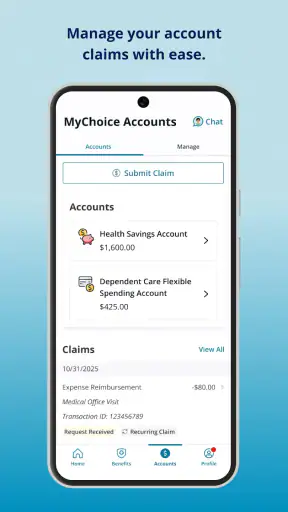
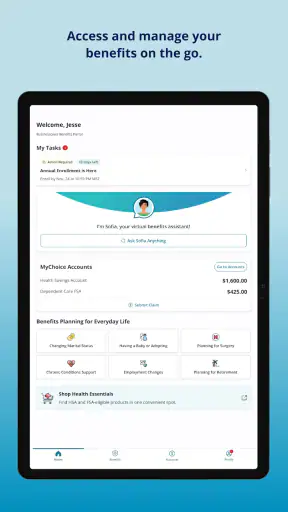
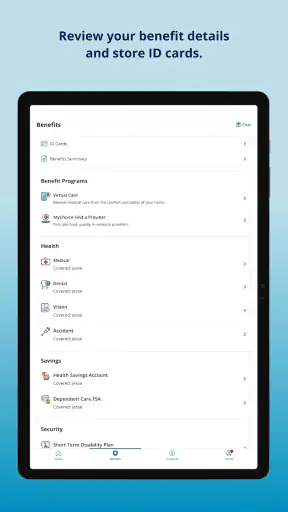
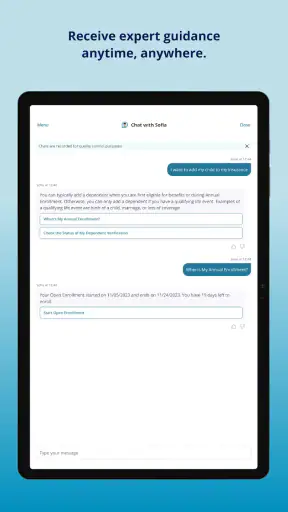
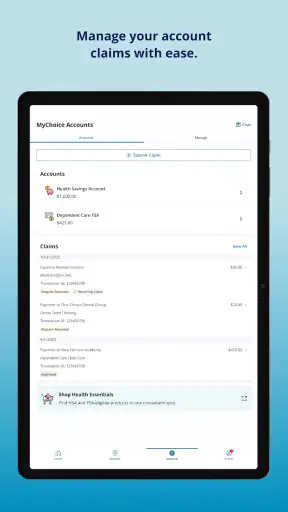
Managing workplace benefits is rarely something people want to spend extra time doing. It usually happens when a deadline is close, a family detail changes, or an unexpected medical expense makes an old coverage choice suddenly important. MyChoice Benefits is built for that narrow but useful job: helping eligible users reach their benefits and enrollment information from a mobile device. I found it most valuable as a practical access point rather than as an all-purpose financial or health app.
That distinction matters. This is a business app from Businessolver, and its usefulness depends heavily on whether your employer’s benefits program supports it. When access is available, the app can make benefit-related tasks easier to approach away from a desktop. When access is not available, installing it will not turn it into a general benefits browser. I would therefore treat eligibility as the first question, before judging the app itself.
The app is free to download and is rated for Everyone, which makes its basic positioning straightforward. It has been available since February 17, 2017, and the current version is 3.5.6 for devices running at least iOS or Android 10, depending on the platform you use. Its 4.7 average from around 8.6 thousand ratings and more than 500 thousand installs suggest that many people find the service useful, although those figures should not replace checking whether it fits your own employer’s setup.
How MyChoice Benefits handles a sensitive workplace task
A focused tool rather than a replacement for every benefits channel
My first impression is that the app makes more sense when viewed as a companion to an employer benefits program. It is not trying to be a general insurance marketplace, a doctor-finding service, or a personal budgeting platform. Its purpose is much more specific: giving eligible users convenient access to benefits and enrollment information.
That focus is a strength because benefits information can become difficult to locate when it is scattered across emails, printed documents, employer portals, and separate provider websites. A dedicated mobile entry point gives users one place to begin. I would especially appreciate that during an enrollment period, when comparing options is easier if I can check information while sitting at the kitchen table rather than waiting to use a work computer.
At the same time, the focused design creates a clear limitation. The app cannot be judged like an independent consumer service. The information available to you is tied to your eligibility and the benefits environment configured for your organization. Two people can install the same application and have very different experiences because their employers provide different plans or access arrangements.
This is also why I would not assume that installing it automatically settles every benefits question. For detailed coverage interpretation, claim disputes, provider-specific matters, or an urgent medical decision, the app should be treated as a starting point for information rather than the only authority. The safest workflow is to use it to locate your relevant details, then verify important decisions through the official plan or employer channel when the consequences are significant.
Trust begins with the account boundary
Because benefits information can reveal personal and family circumstances, I pay attention to where an app’s responsibility begins and ends. MyChoice Benefits is developed by Businessolver, so the app’s role is connected to an organized workplace benefits service rather than an anonymous standalone tool. That context is useful, but it does not mean every user should skip ordinary account caution.
I would install it only from the official app marketplace, use the access route supplied by my employer, and avoid entering benefits information into an unofficial page reached through a random message. A benefits app is exactly the kind of product where a convincing imitation could be more dangerous than an ordinary utility app, because users may be handling enrollment choices and personal information under time pressure.
The app’s age rating of Everyone describes its general store classification, not the sensitivity of every task performed inside it. Adults may use it to manage employment benefits, and some of the information involved can still be private. My practical advice is to keep the device itself protected, use a unique account password where applicable, and sign out or lock the device if it is shared with family members.
I also prefer to review the app’s current privacy and permission screens during installation instead of accepting every prompt automatically. Permissions can change as an app evolves, and the safest choice is to understand what the phone is asking for at the moment of installation. If a permission appears unrelated to accessing benefits information, I would pause and check whether it is optional or necessary before continuing.
What to check before relying on the information
A useful habit is to confirm the context of every benefits detail you view. Look for the relevant plan year, enrollment status, covered dependents, and any dates attached to the information. A mobile screen encourages quick scanning, but benefits choices often depend on small distinctions that are easy to miss when scrolling.
One non-obvious advantage of using a dedicated app is that it can become a review checkpoint before you make a choice elsewhere. I would open it before contacting a provider or submitting an enrollment decision, note the exact wording of the option I am considering, and keep a personal record of the decision and its date. That does not replace official confirmation, but it reduces the chance of relying on an old email or a memory from a previous enrollment period.
Another useful approach is to separate browsing from deciding. I would first review the available information without rushing to change anything, then compare the consequences with my household needs, and only afterward complete an enrollment action if the app presents one. This is particularly important when a choice affects dependents, payroll deductions, or coverage timing.
Everyday scenario: a family change during enrollment
Imagine that I need to review benefits after a change in my household. Instead of searching through workplace messages, I can begin with MyChoice Benefits on my phone, access the information associated with my eligibility, and inspect the enrollment material in a quiet moment. I can check which details need updating, compare the available information with my records, and then decide whether I need to contact my employer’s benefits team.
The value here is not that the phone makes the decision for me. The value is that it reduces the friction of finding the right place to start. If I am traveling, away from my desk, or dealing with the change outside normal office hours, convenient access can prevent the task from being postponed until I forget a deadline.
There is a trade-off, though. A phone is convenient but not always ideal for reading dense plan explanations. I would use the app for quick access and initial review, but switch to a larger screen or official documentation when I need to compare several complicated options line by line. Convenience should not encourage a rushed decision.
Where user control matters most
For a benefits app, user agency is more important than a flashy interface. I want to know what I am viewing, which action I am about to take, and whether the change is informational or consequential. MyChoice Benefits is most helpful when I use it deliberately: checking my status, reviewing enrollment information, and confirming that the account context matches my employer and current circumstances.
Before submitting anything, I would read the final screen carefully rather than tapping through automatically. I would check names, dependents, plan selections, and effective dates where they are shown. If the screen is unclear, I would stop and seek clarification instead of assuming that a later correction will be simple.
This is one of the app’s important practical limits: a mobile workflow can make a serious action feel as casual as changing a phone setting. Benefits enrollment is not casual. Even if the app presents information clearly, the responsibility for checking the result remains with the user. I see that as a reason to use the app carefully, not as a reason to avoid it.
I would also avoid using a public or shared device for account access. If that is unavoidable, I would make sure the session is closed afterward and that no personal notifications or saved credentials remain exposed. These are ordinary precautions, but they matter more when an app connects to employment and household information.
How it compares with the usual alternatives
The most obvious alternative is an employer’s web portal. A browser can be better for long documents, side-by-side comparisons, printing, or completing a detailed form. MyChoice Benefits has the advantage when I need a quick mobile entry point and do not want to locate a saved portal address or sit at a computer.
Email is another common alternative, but it is poor as a long-term filing system. Messages can be buried, links can expire, and older information may no longer match the current enrollment period. An app connected to the benefits service is more purposeful for checking the information associated with the account at the time I need it.
Printed benefits guides remain useful for careful reading and household discussions, especially when several people need to review the same material. They are less convenient when information changes or when I am away from home. In my view, the best arrangement is not app versus paper; it is the app for access, official documents for detailed understanding, and employer support for questions that require interpretation.
I would choose a different option if my main need were broad personal finance management, independent insurance shopping, or medical care navigation. MyChoice Benefits is not the right tool simply because it is free. Its value comes from its connection to eligible workplace benefits, so people without that connection should not expect a useful general-purpose experience.
Practical friction and situations where I would skip it
The first possible obstacle is eligibility. If your employer does not use the relevant Businessolver service or has not enabled access for you, the app is unlikely to solve your problem. I would confirm the official access instructions before spending time troubleshooting an account that may not be supported.
A second source of friction is the small screen. Reading a short status update is easy; understanding several coverage choices can be tiring. I would not make a high-impact decision while distracted, rushing between appointments, or relying only on a partial view of the information.
A third consideration is account dependence. If you change jobs, lose eligibility, or encounter an employer-side configuration issue, the app’s usefulness may change with that relationship. That is normal for a workplace benefits tool, but it means I would keep important personal records and confirmation details rather than treating the app as my only archive.
I would skip it as a primary solution if I wanted a service that combines multiple unrelated insurance providers, gives independent plan recommendations, or offers extensive financial planning. The narrow scope is not a flaw for its intended audience, but it becomes a mismatch when the user expects a broader service.
My considered verdict for eligible users
MyChoice Benefits earns its place on a phone when it gives an eligible employee a dependable, convenient route to workplace benefits and enrollment information. I like the practical focus, the free access, and the way a mobile entry point can make an easily postponed task more approachable. Businessolver has built a product aimed at a real moment of need rather than at entertainment or constant daily use.
My recommendation comes with a clear condition: use it as an informed access tool, not as permission to rush. Check the account context, review privacy and device controls, verify important details, and move to official support or larger documentation when a decision is complicated. The app can reduce searching and delay, but it cannot replace careful reading or personal judgment.
With that mindset, I would recommend it to eligible employees who want benefits information close at hand, particularly during enrollment or household changes. I would not recommend installing it blindly to someone whose employer has not confirmed support, nor would I suggest relying on it alone for disputes or complex coverage interpretation. For the right user, its strongest quality is simple: it puts a focused benefits workflow where many people already look first, while still leaving the important choices in the user’s hands.
My bottom line: if you are eligible, MyChoice Benefits is worth trying as a convenient and cautious companion to your employer’s benefits process. Its 4.7 average and broad adoption are encouraging signs, but the real test is whether it gives you clear access to your own plan information without making you forget to verify the details that matter.
4.7
1.11K Reviews
Pros
- Centralizes health
- insurance
- and voluntary benefits in one place.
- Personalized benefit information makes plan details easier to find.
- Useful enrollment support during annual benefits selection periods.
- May provide access to benefit documents and important account resources.
- Can help employees compare available options before making elections.
Cons
- Available features depend heavily on the employer’s benefits setup.
- Some users may need separate provider apps for claims or account management.
- Benefit terminology can still be confusing without additional guidance.
- Login or verification issues may prevent quick access to account information.
- Certain tools and resources may not be available outside enrollment periods.


